$100 - $100,000
CS: 0 • 5.96% - 35.99%
If you suffer unexpected financial hardship, there are affordable options to help you weather the storm. For example, if you need $50, $100, or $300, you may think that payday loans are your only option. However, several reliable cash advance apps help finance borrowers with bad credit.
| Loan App: | Amount: | APR: | Fees: | Credit Check: |
|---|---|---|---|---|
MoneyLion

|
$25 – $1,000 | 0% | $0/mo. $0.49 to $8.99 for immediate cash advances |
No |
Brigit

|
Up to $250 | 0% | $9.99/mo. | No |
Earnin
|
Up to $150/Day or $750/Period | 0% | $0/mo. Up to $3.99 per $100 for same-day cash advances (first is free) |
No |
Current

|
$50 – $500 | 0% | $4.99/mo. | No |
Cleo

|
$20 – $250 | 0% | $5.99/mo. $3.99 for same-day cash advances |
No |
Dave

|
Up to $500 | 0% | $1/mo. $1.99 to $5.99 for same-day cash advances |
No |
SoLo Funds

|
Up to $500 | 3% – 10% | $0/mo. Late payment fee is 15% of the loan amount + $5 |
No |
Possible

|
Up to $500 | 150% – 200% | $0/mo. | No |
Vola

|
Up to $300 | 0% | $4.99/mo. | No |
Varo

|
Up to $500 | 0% | $0/mo. $1.60 – $40 | No |
Albert

|
Up to $250 | 0% | $0/mo. $6.99 per cash advance to an external bank account |
No |
Chime

|
Up to $200 | 0% | $0/mo. | No |
Branch

|
Up to $150/Day or $500/Period | 0% | $0/mo. $2.99 to $4.99 for same-day cash advances to an external bank account |
No |
Extra

|
Varies by Bank Balance | 0% | $7/mo. | No |
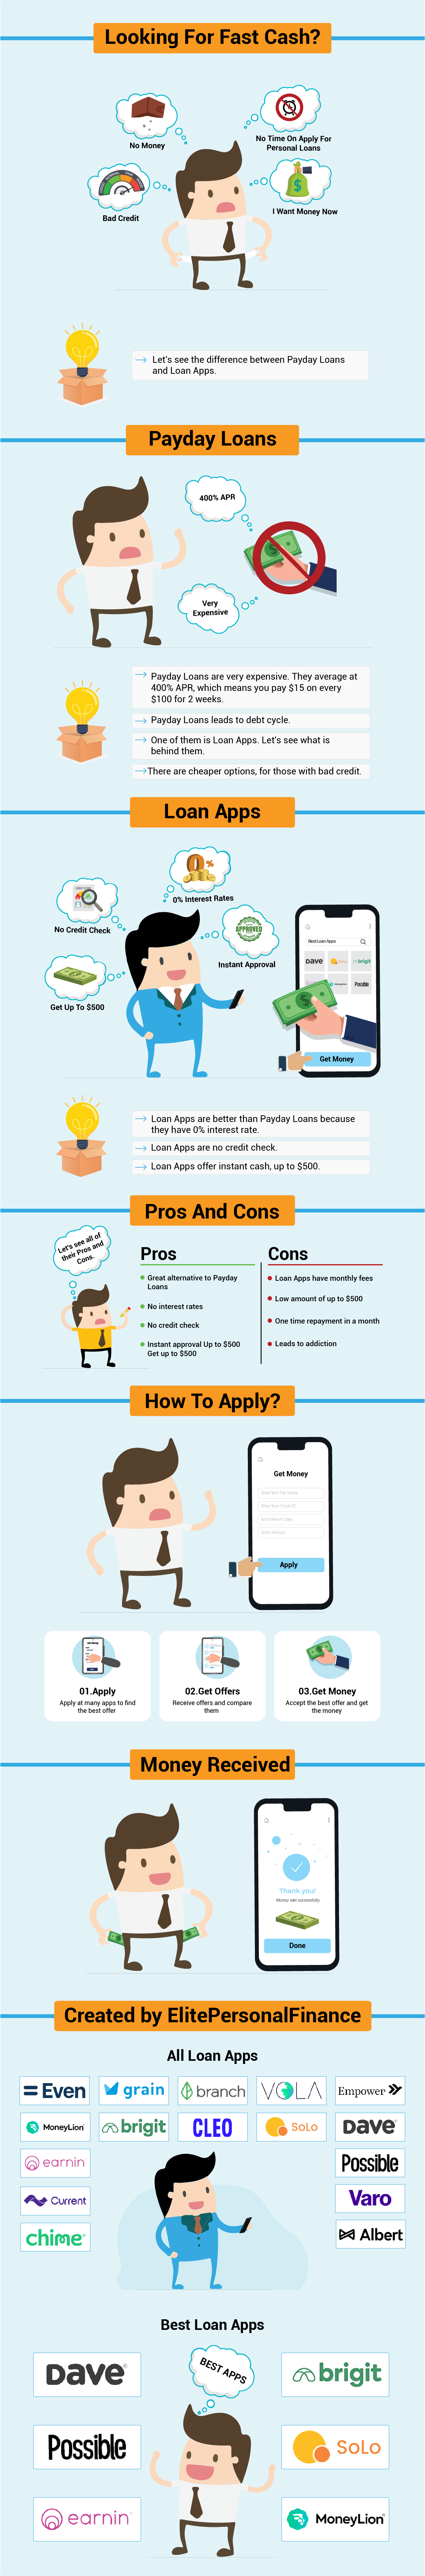
For your reference, ElitePersonalFinance continuously scans the marketplace to find payday loan alternatives for people with bad credit. And if you’re unfamiliar, payday loans have an average APR of 400% and can trap you in a cycle of debt. Along the way, they can also ruin your credit.
Conversely, cash advance apps offer affordable financing and reasonable terms. As a result, apps like Dave, Brigit, Earnin, and MoneyLion can provide funds to hold you over until your next paycheck arrives.
Pros:
Cons:
Thus, before submitting your application, you should consider all of your options. For example, personal loans have higher loan amounts of up to $100,000 and can even reach upwards of $250,000 under certain circumstances. Moreover, repayment terms are much more flexible, and cheap APRs of 5.99% to 35.99% make personal loans more affordable than payday loans. Therefore, please visit our marketplace and browse your available options to learn more.
While there are plenty of cash advance apps in the marketplace, there are also plenty of scams. For example, bad actors try to take advantage of the momentum when an industry experiences rapid growth. Moreover, we found that some cash advance apps are payday loan sites in disguise.
But how do you spot them?
If you find an app that mentions a 400% APR, it’s a payday loan provider. And we recommenced that you avoid these platforms, as there are much better options available.
ElitePersonalFinance only covers legitimate cash advance apps. We don’t list or review any payday loan apps!
Like Dave, MoneyLion Instacash can spot you $25 – $1,000 with no interest or credit check, and the app should be functional in all states. However, the only repayment option is to have MoneyLion automatically deduct the funds from your next paycheck. To qualify, you need to link an external checking account open for at least two months, and it has to remain active and maintain a positive balance. Also, MoneyLion restricts new accounts to $25 or slightly more at the outset. However, once you build a reliable history, you’ll have access to $50 and then up to $1,000. For context, the company notes that it can take three to eight weeks to qualify for the $25 – $1,000 Instacash maximum.
Moreover, there are no standard fees to receive your funds. For example, regular delivery is three to five business days or 12 to 24 hours under certain circumstances. However, like Dave and Earnin, charges for immediate access apply. They range from $0.49 for cash advances of $5 or less to $8.99 for $100 or more.
For your reference, MoneyLion has a Credit-Builder account tailored to individuals with bad credit. It costs $19.99 per month, provides access to personal loans of up to $100,000, and has APRs ranging from 5.99% to 29.99%. Moreover, the company found that more than 50% of its borrowers increased their credit score by 42 points (or more) within 60 days. As a result, if you need longer-term financing, MoneyLion may be a suitable option. However, our marketplace has similar products that don’t require a monthly membership fee if you’re interested.
Pros:
Cons:
Like Dave and MoneyLion, Brigit also offers cash advances of up to $250, with no interest or credit check. Moreover, you can repay the advance manually or have the funds automatically deducted from your next paycheck. Furthermore, the Brigit app should be functional in all states. However, to qualify, there are a few stipulations. You need to have a checking account and use it daily. In addition, you need to have at least 60 days of activity and maintain a positive balance. Moreover, it’s crucial to have a cash surplus every two weeks after receiving your paycheck.
On top of that, Brigit determines your eligibility by analyzing your “Brigit Score.” For example, scores range from 0 to 100, and Brigit doesn’t specify a minimum to qualify. However, the alternative lender notes that the most successful scores range from 40 to 100.
Also, please consider that you can only have one cash advance at a time, and you can’t obtain a new one until you repay the old one in full. However, approved borrowers should receive the funds within one to three business days. Moreover, unlike Dave, Brigit offers no-fee instant funding that you can receive in as little as 20 minutes. On the flip side, Brigit is like Vola and Cleo because it has a monthly membership fee of more than $4. For example, you need to pay $9.99 per month to access cash advances.
Pros:
Cons:
As another excellent cash advance app, Earnin allows you to access up to $100 per day, and like SoloFunds, $750 per pay period. You need a checking account and frequent direct deposits to qualify. However, if approved, there is no interest. Like Dave, you can repay the advance manually, or Earnin will automatically deduct the funds from your next paycheck. In addition, Earnin doesn’t list any monthly membership fees, and like the other apps on our list, its products should be available in all states. However, the company encourages users to provide a tip when receiving their funds, though this is voluntary.
In addition, standard cash outs provide funds in one to three business days, and your first same-day cash out is free. After that, the maximum fee is $3.99 per $100 cash advance. As a result, if you have stable earnings and meet the qualifications, Earnin is a solid option. Moreover, the company doesn’t charge a monthly fee to access cash advances, so like MoneyLion, it’s cheaper than Brigit and slightly cheaper than Dave.
However, please note that Earnin requires privacy disclosures. For example, the company analyzes your work email, timesheets, wage stubs, and GPS locations to verify your income and workplace attendance. Of course, this requires your approval. As a result, if you’re uncomfortable with this level of scrutiny, you should consider the drawbacks before signing up.
Pros:
Cons:
With the same benefits and different terminology, Current doesn’t offer cash advances like Varo and Cleo. However, “Overdrive” still provides $50 – $500 in fee-free overdraft protection. To qualify, you need to sign up for Current Premium, which like Vola, costs $4.99 per month. In addition, you need to have at least $500 in qualifying monthly direct deposits. For context, these include payroll or social security benefits. Likewise, since Current’s overdraft service only applies to purchases made with your Current debit card, linking an external bank account is likely out of the question.
Conversely, there is no interest or credit check, and there are no additional withdrawal expenses. Moreover, like MoneyLion, Current will deduct the repayment from your next paycheck, and the app should be functional in all states. However, please note that new members will start with $25 in Overdrive protection, and Current will decide when/if you can make the jump $500. As a result, while Current takes a responsible approach to extending credit, it may be easier to gain approval through other apps.
Pros:
Cons:
Cleo is like Current and Varo because it provides cash advances of $20 – $250. Moreover, there is no interest or credit check, and the app should be functional in all states. However, please note that new members usually qualify for $20 to $70 until they build a reliable history. But if you demonstrate prudent repayment habits, you shouldn’t have any problem getting the total of $100. Moreover, you can repay the advance manually, or Cleo will automatically deduct the funds from your next paycheck.
However, your eligibility depends on your spending habits, payroll, and how well you budget. But if you qualify, you can receive the funds in four business days free of charge or have instant access by paying $3.99 per cash advance. One of the downsides is that you need to pay a $5.99 monthly subscription fee, which is higher than other companies on our list like Dave and Vola. Another is that Cleo doesn’t list any options to link an external bank account, so, like Chime, you need to bank with Cleo to access its cash advance service.
All in all, the cost of the subscription is lower than what you’ll pay in overdraft charges. And Cleo Plus offers access to exclusive cash-back deals from popular stores. As a result, you can often earn back the $5.99 monthly fee if you spend $100 or more per month on eligible cash-back purchases. Moreover, you can also opt for a secured credit card as part of Cleo’s $14.99 per month subscription package. However, Cleo’s Credit Builder card limit depends on the amount you deposit, and it isn’t much different from other secured credit cards in the marketplace.
Pros:
Cons:
Dave is like MoneyLion because it provides cash advances of up to $500, with no interest and no credit check. To qualify, you need to provide your direct deposit information and have at least two qualifying direct deposits. After that, Dave will analyze your income and determine if you are eligible for a cash advance. For context, you need to demonstrate that you have cash left over after paying your bills. If not, Dave may not approve your application. However, if you’re approved, standard funding is free, taking up to three business days. Conversely, express deposits provide same-day financing, but like Earnin and MoneyLion, there is an extra charge. For example, the fee ranges from $1.99 for cash advances of $5 or less to $5.99 for $100 to $500.
But does Dave work with Capital One? Yes, Dave allows you to link several checking accounts that meet the requirements above. Thus, whether you bank with Capital One, Chase Bank, or Bank of America, you shouldn’t have any problems merging your account with Dave.
Also, cash advances are only open to Dave members. And membership costs $1 per month. In addition, you can also provide periodic tips, though it’s not a requirement. Moreover, you can repay the advance manually or, like Brigit, have Dave automatically deduct the funds from your next paycheck.
All in all, Dave is a reliable service that can help bridge the gap between paychecks. As a result, if you have a steady job and can demonstrate a predictable income, Dave can save you money relative to a payday loan. Furthermore, the Dave app should be functional in all states.
Pros:
Cons:
Operating a different business model than the other apps on our list, SoLo Funds is a peer-to-peer (P2P) lender that connects you with ‘investors’ willing to help. For example, loan amounts range from $50 to $500, repayment terms max out at 15 days, and you don’t need a credit score to qualify. Moreover, like Dave, same-day funding is usually an option, and the app should be functional in all states. In addition, tips typically range from 3% to a 10% maximum. But since they are not mandatory, you may score a 0% APR under optimal circumstances.
However, please note that late payment fees are 15% of the loan amount plus $5. As a result, if you borrow $100 and can’t meet your repayment deadline, the $20 penalty bumps your expense rate up another 20%. Moreover, unlike payday loans, you can’t roll over your loan if you default. However, it’s probably for the best since it keeps you from amassing charges upon charges that could exceed the initial loan amount. Also, please remember that defaulting on your loan may disqualify you from obtaining future financing.
Pros:
Cons:
Possible offers loans of up to $500, and like SoloFunds, there is no credit check, and financing is obtainable by individuals with bad credit. However, loan amounts vary by state and max at $250 in California. Thus, it’s essential to contact Possible before you submit your application. Also, some applications are approved in minutes, while others can take up to five business days. Moreover, Possible reports your repayment behavior to the major credit bureaus, so your hard work will be rewarded if you pay on time.
Conversely, the downside is that Possible’s APRs range from 150% to 200%, so loan apps like Dave and MoneyLion are cheaper options. However, since payday loans have an average APR of 400%, it’s a decent fallback option. In addition, Possible allows you to repay your loan over eight weeks, and there is a 29-day grace period if you run into financial trouble. In contrast, payday lenders usually require repayment in two weeks, and hefty penalty fees can apply if you miss a payment.
You need a checking account at least three months old with direct deposits of $750 per month or more to qualify. Also, having a balance surplus each month can increase your approval odds. For your reference, the company’s disclosures note that loans are only available in select states: “At the moment Possible is available in Alabama, California, Delaware, Florida, Idaho, Indiana, Iowa, Kansas, Kentucky, Louisiana, Michigan, Mississippi, Missouri, Ohio, Oklahoma, Rhode Island, South Carolina, Tennessee, Texas, Utah, and Washington.”
So, overall, Possible’s APRs are pretty high, and you’re better off browsing the bad credit personal loans that we have in our marketplace. However, if your only choice is Possible or a payday loan, the former is better.
Pros:
Cons:
Offering cash advances of up to $300, Vola has your back when you need short-term financing. For example, its products are like Dave and MoneyLion’s offerings because there is no interest or credit check associated with your loan, and the app should be functional in all states. However, cash advances are only available to Vola members, and a subscription costs $4.99 per month.
Moreover, to qualify, you need to link a checking account at least three months old. In addition, you must maintain regular activity, have an average balance of more than $150, and have steady income deposited in the account. However, as part of your monthly membership, you can receive your loan proceeds in five business hours or less. Furthermore, please note that, like Dave, Vola will automatically deduct the funds from your next paycheck, or you can make manual repayments at an earlier date.
And like Brigit, Vola tracks your progress using a proprietary scoring method. For example, the more you read Vola’s educational content, increase your average balance, and avoid non-sufficient funds (NSF) fees, the more your Vola Score increases. Likewise, the company notes that individuals with higher scores are “eligible for more benefits” on the platform.
Pros:
Cons:
Like Cleo and Current, Varo extends short-term financing of up to $500. Moreover, there is no interest or credit check, and unlike many of the other cash advance apps on our list, you can choose a repayment date that ranges from 15 to 30 days after receiving the funds. However, while there are no late payment or penalty fees, there are tired administrative fees $1.60 – $40.
To qualify, you have to have an Active Varo Bank Account with a positive balance and at least $800 in total qualifying direct deposits from the current or previous month. Additional qualifications apply. However, approved borrowers can opt for free same-day funding, and, like Dave and MoneyLion, the app should be functional in all states.
Pros:
Cons:
Albert rivals companies like Dave and MoneyLion because you can borrow up to $250 with no interest or credit check, and the app should be functional in all states. Moreover, like Dave, you can repay the advance manually or have the funds automatically deducted from your next paycheck. In addition, there are no late payment fees, but you can leave a voluntary tip. However, please note a $6.99 administrative fee for cash advances applies for deposits to an external bank account.
To qualify, you need a linked bank account with a positive balance open for at least two months. Moreover, you need to have regular direct deposits from the same employer, and you must have an account surplus the day after your paycheck arrives. Then, if approved, you can receive your funds in two to three business days. However, for expedited deposits, there is another “small fee.”
Pros:
Cons:
As a hybrid feature similar to a cash advance, Chime’s SpotMe program offers up to $200 in overdraft protection, and like Dave, the app should be functional in all states. Now, you need an in-house checking account for loan apps that work with Chime. However, if you already bank with Chime, SpotMe can save you a bundle in fees.
For example, most members that have direct deposits of at least $200 per month can enroll in SpotMe. Moreover, if your checking account balance dips into negative territory, Chime will provide you with an advance of up to $200 to bring the balance back to even. Then when your next direct deposit arrives, Chime pays itself back.
Furthermore, don’t worry about fees, interest, or credit checks, and debit purchases and cash withdrawals are eligible. However, please note that payments to friends don’t qualify. In addition, you can leave Chime a tip, but like Albert, the action is voluntary and not a requirement.
Pros:
Cons:
If you need money between paychecks, Branch can help cover the shortfall. For example, Branch offers no-interest cash advances, and there is no charge to receive the funds within three business days. And like MoneyLion, Branch will automatically deduct the funds from your next paycheck, and the app should be functional in all states.
To qualify, the same employer needs to make two months of direct deposits of at least $40 into your checking account, and your debit card needs to match. As well, you need to input your workplace location. However, as long as the disclosure is correct, it won’t cause any issues when you work from home. Moreover, Branch notes that low budgets and high spending activity can reduce your odds of qualifying for a cash advance. As a result, you should consider a prudent banking history as one of the requirements.
Like Earnin, cash advances max at $150 per day and $500 during the pay period. And if you have a Branch debit card and digital wallet, you get free same-day funding. However, if you want instant access to your funds and have an external bank account, the charges vary from $2.99 to $4.99.
In contrast, there are no monthly fees, and like Albert, tips are voluntary. In addition, since Branch doesn’t consider the transaction a loan, it shouldn’t require a credit check.
Pros:
Cons:
Home to a debit card that functions like a credit card, Extra’s credit-building service works with more than 10,000 banks across the U.S. As a result, the Extra app should be functional in all states. It works like this: you link your external bank account to Extra’s app, and the company’s algorithm will analyze your spending behavior. After that, Even applies a purchase limit to your Extra card. Then, when you go shopping, you pay with your Extra card, and the company will deduct the funds from your bank account the next day. The benefit of the service is that Extra reports your spending habits as credit purchases. As a result, agencies like Experian, Equifax, and TransUnion will be aware of the transactions, and like Possible, the disclosures can help boost your credit score.
Moreover, there is no interest or credit check. However, Extra’s cheapest membership fee is $7 per month. Extra has one of the highest monthly charges on our list. But it’s still a win-win for people trying to build credit. Thus, if you have bad credit and can’t get approved elsewhere, Extra can help you rebuild your reputation, allowing you to qualify for more affordable loans in the future.
Pros:
Cons:
Yes. Some of the cash advance apps in our study have no interest or fees, while others have no fees but charge for monthly subscriptions. As a result, while all apps are better than payday loans, those with low or no membership fees (like Dave and MoneyLion) stand out from the competition.
Thus, please think of our list as broken down into three groups:
As a result, Possible is in the third group. For example, with APRs that range from 150% to 200%, we recommend that you only use the app as a last resort. However, since it’s an alternative payday lender with lower interest rates and better terms than a payday loan, we felt it was prudent to let you know that the option exists.
No. At ElitePersonalFinance, we want to help you find the cheapest loans available. And to meet our criteria, products need to have low APRs, flexible terms and originate from a reputable lender. Thus, our marketplace has several options that meet these requirements.
Conversely, we don’t and never will recommend payday loans. And when it comes to high APR alternative payday loans like Possible, we only recommend them for emergencies.
Moreover, if you have bad credit, you may not know that several lenders are willing to offer you affordable financing. As a result, please browse our marketplace or contact us if you have any questions. In addition, if you want to learn more about the options available, please consult our guides below:
In addition, for a quick rundown of the best options available, our marketplace includes several lenders that can help:
Cash advance apps provide short-term funding until your next paycheck arrives. Amounts often range from $5 to $300, and some companies will let you repay the balance in 30 days.
However, the critical point is that these products are for short-term financing. Moreover, all companies on our list require proof of payroll or government benefits to approve your application. Thus, if you have regular income and suffer unexpected expenses, these apps can help until your next payroll deposit arrives.
Also, please keep in mind that the small payouts won’t provide much of a financial cushion. For example, if your car breaks down, your roof suffers a leak, or an unfortunate accident leaves you with a hefty medical bill, $300 likely won’t be enough. However, if you’re short on rent and only need a few hundred dollars, cash advance apps can help.
All in all, the products should be thought of as bridge financing. Thus, if you’re in a tight spot and need cash quickly, they can keep you going until payday.
No. Most cash advance apps do not conduct credit checks. For context, non of the lenders on our list perform a credit check. Instead, they monitor your bank balance and perform cash flow analysis. It works like this: cash advance apps’ algorithms quickly scan your account history and determine the surpluses and deficits that you carry each month. In addition, companies’ algorithms may also have proprietary metrics that they use. Then, if they determine that your spending and savings habits meet their criteria, they will extend credit due to the expectation that you can repay the funds.
And that’s all there is to it. As long as your cash flow metrics come back clean, there is little need to analyze your credit score.
Yes. As mentioned above, lenders care more about your cash flow than your credit score. As a result, if you have bad credit or no credit, it won’t stop you from gaining approval. Now, instant approval is uncertain, and not all applicants will qualify. However, if you meet the company’s banking criteria and maintain a positive account balance during most weeks and on payday, you shouldn’t have any problem obtaining a cash advance.
Moreover, these companies fill a void in the lending market. For example, some traditional lenders shun borrowers with bad credit. And unfortunately, one slip hurts your chances of obtaining affordable loans. However, cash advance apps realize that many borrowers are underserviced and want to help. As a result, your credit score matters much less to them, and cash advance apps can act as a bridge to rebuilding your credit.
Unfortunately, many cash advance apps charge a fee for instant access to your funds. Conversely, if you wait for one to four business days, you can receive the money free of charge. However, in our opinion, the policy is kind of disappointing. For example, many of these companies advertise saving on overdraft fees by using the apps. And they’re right.
However, instant access to your cash is why you’re applying in the first place. If you didn’t need the money right away, you would wait until payday. As a result, waiting for one to four business days may not fit your needs. And since many lenders know this, it’s an opportunity for them to make money by capitalizing on your desperation.
Thus, the product almost defeats the purpose in some ways: if you could plan for when you need cash, you would never apply for an advance. Moreover, when an unfortunate event occurs, the fee worsens the unpleasant situation. As a result, while cash advance apps are helpful under certain circumstances, they don’t consistently deliver the best results.
For a quick rundown of the benefits and pitfalls of cash advance apps, please consult our list below:
Pros:
Cons:
Absolutely. And we can’t stress this enough. While cash advance apps have good and bad qualities, they’re much cheaper than payday loans.
For example, payday loans have an average APR of 400%, and your interest expense is more than 10x higher than a bad credit personal loan. Likewise, payday loans often have hefty penalty fees that add to your outstanding balance every two weeks. As a result, if you take out a $300 payday loan, most lenders will charge $45 (15% interest rate over two weeks). But, if you can’t repay at maturity, you may incur a penalty fee of $45. Thus, your total balance owing is $390, and the vicious circle can continue for months. Sometimes, borrowers pay fees that exceed the original loan proceeds.
Conversely, cash advance apps have clearly defined parameters, and your loan is repaid directly from your next paycheck. Moreover, an app like Dave has a membership fee of $1 per month. So on a $250 cash advance, it only costs you $1 in fees (0.40% interest rate over two weeks). Likewise, even though Brigit has the highest membership fee on our list at $9.99, a cash advance of $250 only results in a roughly 4% interest rate over two weeks.
As a result, if someone offers you a payday loan, you should run, not walk, in the other direction.
Yes. Some cash advance apps have no interest, fees, or credit checks. Moreover, even the cash advance apps that charge a monthly subscription fee are cheaper than alternative payday loans.
For example, if you pay $4.99 per month for a Vola membership, you can qualify for a cash advance of up to $300. And that works out to roughly $1.66 per $100 borrowed over two weeks. Conversely, a loan from Possible with a 151% APR results in $15 in expenses for every $100 borrowed over eight weeks. As a result, the more extended payback period still results in higher sunk costs. Thus, with cash advances from Dave and MoneyLion even cheaper than Vola, you should only consider an alternative payday loan if you have no other option.
Separating the good from the great comes down to your personal preferences. For example, paying a membership fee at Brigit and Vola, may work for you if you want additional banking services. However, if your sole focus is to obtain the cheapest short-term financing, we like to focus on a few criteria.
The value proposition:
We want the best product that offers the lowest fees. For example, Earnin provides cash advances of up to $500, which is higher than other lenders on our list, and it doesn’t have a monthly membership fee. Likewise, MoneyLion offers cash advances of up to $250 with no monthly membership fee. As a result, the pair offer borrowers the best bang for their buck.
Banking freedom:
When creating our list, we noticed that some cash advance apps let you link an external bank account, and others require you to bank directly with them. For example, Chime’s SpotMe cash advance service is an additional feature that works with its other products. Conversely, MoneyLion and Dave have stand-alone cash advance services that work with external bank accounts. As a result, the latter two offer more freedom.
Security:
Since cash advance apps are relatively new, spotty regulations can be harmful. As a result, some of the protections you have with traditional banks, credit card companies, and established lenders may not apply with cash advance apps. Thus, it’s critical to determine the least risky companies.
Dave and MoneyLion’s partner banks are Federal Deposit Insurance Corporation (FDIC) members. Therefore, it gives us confidence that the pair adhere to regulatory standards and have met the minimum requirements of trustworthy institutions.
The verdict:
We think that Dave and MoneyLion check off the most boxes. They have the lowest fees, allow you to link an external bank account, and have their activities overseen by the FDIC. So, as a result, they should be the first options you consider.
When a loan app offers you a no-interest cash advance and even waives late fees, isn’t there a catch? Don’t worry. Like most 0% APR lenders, loan apps find other ways to monetize their services.
Word of mouth:
When cash advance apps experience robust growth, they offer their customers ancillary services. And this generates more revenue as users take advantage of the platform’s other features. Then, as word spreads, the apps become more popular online, with users and personal finance websites recommending them. Therefore, it helps sustain growth and increases brand awareness. However, we only recommend cash advance apps based on merit. If a platform has less-than-stellar service, we don’t include it in our guides.
Membership fees:
If you read the reviews above, you can see that several lenders charge membership fees to access cash advances. However, the practice is pretty standard. When consolidating several services, loan apps encourage prospects to pay for bundles. Think of it like Amazon Prime: while some members may sign up for the free one-or-two-day shipping, others do so to watch Prime Video, listen to Prime Music, or enjoy Prime Reading. As a result, cash advance apps are no different. Whether it’s budgeting tools, cash advances, or exclusive cash-back shopping offers, no-interest loan apps earn most of their revenue through membership fees.
Tips:
As a play on members’ generosity, voluntary tips can also increase lenders’ revenue. For example, when you dine at a restaurant or have food delivered, most connoisseurs will add a tip to their bill. Therefore, loan apps hope you will do the same for them. However, since tip revenue is much more volatile than membership revenue, the former likely fluctuates materially from month to month.
Advertisements:
With eyeballs the most critical metric in the advertising space, the more you use an app, the more management can charge advertisers for product placements. As a result, lenders often monetize their platforms through ads, whether direct ads for a specific product or indirect ads such as cash-back offers.
Data:
Data is king in the Fintech world. And whether it’s Google, Facebook, or Amazon, what you do and how you do it is of immense value to the platform. For example, loan apps can use your viewing habits to determine which products sell and which don’t. In addition, they can use the data to teach advertisers which strategies are most effective. Overall, many technology companies are willing to offer free services due to the valuable insights they obtain by monitoring your browsing behavior.
While cash advance apps are the latest invention to disrupt the lending market, there is a lot to like. Many have no interest, no credit check, and even function with your traditional bank account. However, the downside is that loan amounts are small, and the repayment terms are short. As a result, if you need more significant proceeds and want more flexible terms, a personal loan may be suitable. Conversely, cash advance apps make life easier if you only need a few hundred dollars to assist until payday.